
Choosing card machines Worthing businesses can depend on is not only about accepting a card at the counter. The right setup has to fit the way you actually trade: where customers pay, how busy periods feel, whether staff move around the premises, how refunds are handled and how sales information reaches the person who reconciles the day.
A caf? near the seafront, a salon, an independent retailer, a restaurant and a mobile service business may all take card payments, but they do not need the same workflow. A useful decision begins with the customer?s payment moment and follows it through to receipts, reports, support and ownership. That is more reliable than choosing from a headline promise.
This guide gives Worthing business owners a practical checklist. It does not quote payment rates, device prices or contract terms, because a proper payment package must be structured around the business, its trading pattern and the wider system it needs.
Contents
Begin with the moment a customer wants to pay
Walk through a normal sale from the customer?s point of view. Do they pay at a fixed counter, at the table, beside a treatment chair, at a collection point, at an event, in a vehicle or after an invoice? Does the team need to move the device to the customer? Are there queues at particular times? Do you need to print a receipt, send one digitally or add a reference that makes the sale easier to find later?
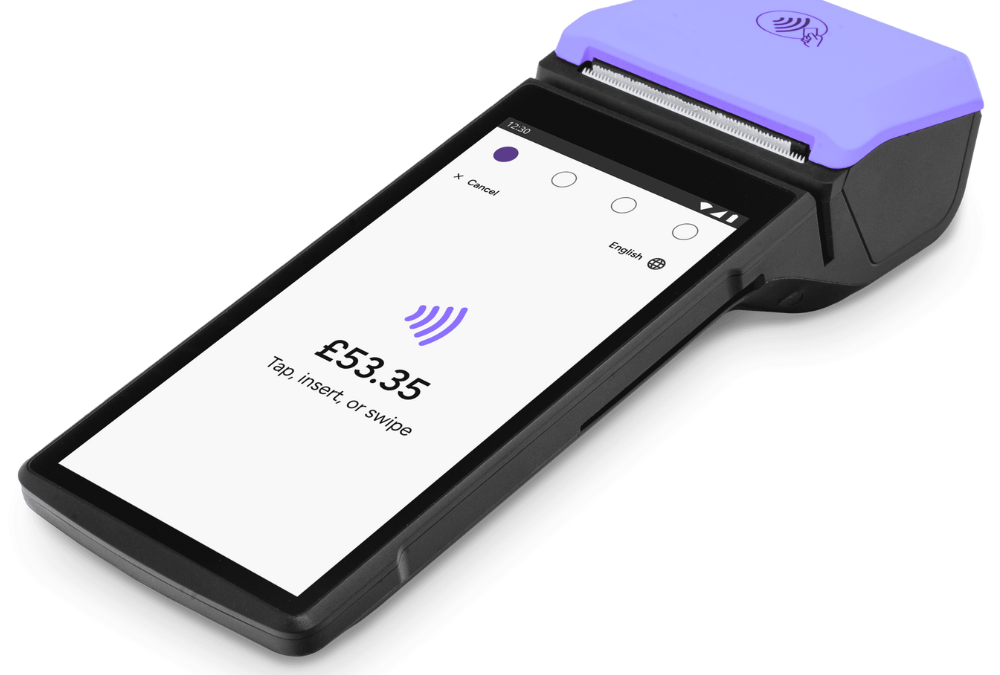
Those answers lead to a more useful conversation about card machines Worthing businesses need. A fixed countertop terminal can suit a single till position. A portable device may make service smoother in a restaurant, salon or busy shop floor. A mobile trading setup may need a dependable way to work away from the premises. The question is not which device looks best in a brochure; it is whether the payment step reduces friction for customers and staff.
Write down the busy-period scenario as well as the quiet one. For example: two members of staff are serving, a customer needs a refund, another wants a receipt, and a manager is not present. If the process is clear in that situation, it is much more likely to work every day.
Choose the setup for the way you trade
Most small businesses have a mixture of payment situations. A retail counter may need speed and a clear checkout position. A restaurant may need staff to take payment at the table without losing the bill reference. A service business may need to take a deposit, then a final payment later. A business with more than one site needs transactions and reports to stay understandable across locations.
Before comparing card machines Worthing options, list the places and moments where payment happens. Include temporary positions such as pop-ups, market days or busy seasonal periods. Then decide whether the terminal needs to work alone or alongside an EPOS system. When products, orders, discounts and staff activity are recorded in the same workflow, the end-of-day review can be much easier than when a terminal and till are treated as separate islands.
If customers place an order themselves, think about the handover between self-service and payment. Our self-service kiosk guidance explains why the customer journey needs a clear exception route when an item is unavailable, a customer needs help or an order must be corrected.
Check connectivity before the busy period
Payments cannot depend on an assumption about signal or Wi-Fi. Check the actual trading location: behind the counter, near tables, in a treatment room, at the door and in any outside area used by customers. Ask what happens if the usual connection is interrupted, how staff will recognise a problem and what the agreed fallback is. The right answer depends on the setup, but the process should be agreed before customers are waiting.
Connectivity is also a support question. Who is responsible for checking the terminal is charged, connected and ready at the start of a shift? Who can call for help if a device stops working? Who records a fault and tells the next team member what happened? These are small operational details, but they often decide whether a payment issue becomes a short interruption or a stressful service failure.
The National Cyber Security Centre?s guidance for small organisations is a useful reference for managing business devices, accounts, passwords and software updates. Treat payment equipment as part of that operational routine, not as an object that only matters on installation day.
That test keeps card machines Worthing businesses choose tied to a real customer journey rather than a generic device list.
Make checkout clear for customers and staff
A good checkout feels simple because the work behind it is clear. Customers should know where to stand, what they are paying for and whether the payment has completed. Staff should know how to select the right sale, confirm the amount, offer a receipt and deal with a declined or interrupted attempt without guessing.
Look at the counter from both sides. Is the display positioned sensibly? Is there enough room to complete a payment without passing a device awkwardly around? Can a customer with a pram, mobility need or limited reach complete the action comfortably? Does the terminal create a queue because staff have to enter the same information twice? These practical checks matter more than cosmetic features when selecting card machines Worthing businesses will use throughout the day.
For a business that combines payments with an online enquiry or booking route, the website should make the next step just as clear. Our web design and development work focuses on customer journeys rather than a homepage in isolation, which is important when the sale begins online and finishes in person.
Understand refunds, voids and corrections before you need them
Every team needs a plain process for a mistake. A customer may have been charged for the wrong item, changed their mind, returned a product or paid twice after a connection issue. If staff do not know the difference between cancelling a sale before it completes, processing a refund and correcting an order record, the financial trail becomes hard to follow.
Ask a prospective provider to explain the exact route for the situations you see most often. Who can approve a refund? Is a reason recorded? Where does the transaction appear in the daily report? How is the customer receipt handled? Can a manager see the activity without having to reconstruct the story from memory? These are good questions for any card-payment setup and should form part of a practical comparison of card machines Worthing businesses are considering.
Clear controls protect customers and the business. They are not about making staff feel watched; they make it possible to understand an exception quickly when the end-of-day totals do not look right. The PCI Security Standards Council?s merchant resources provide reputable background on protecting card data. Staff should never write down, store or ask customers to send card details through informal channels.
Plan how the payment record reaches your daily reporting
Taking a payment is only the first half of the job. At closing time, somebody needs to know what was sold, what was refunded, what remains open and whether the records match the way the business traded. When a terminal, a till, an ordering process and staff notes are disconnected, reconciliation can become a slow search for missing context.
Decide which person checks the daily result and what they compare. In a simple setup, that might mean sales, refunds and receipt references. In a more integrated setup, it may include product sales, tables, staff shifts, delivery channels and stock movement. The daily EPOS reports guide sets out five reports that turn this review into a useful routine rather than a last-minute total.
For card machines Worthing businesses, the useful question is not ?Can I get a report?? Most systems can produce something. Ask whether the report answers the real management question: what happened today, which exceptions need checking and who is responsible for the next action.
Keep staff access proportionate
Not every team member needs the same ability to change prices, issue refunds, close a day or alter device settings. Set roles that reflect the work people actually do. A new team member may need to take payment and print a receipt, while a supervisor may be able to approve a return. The owner or manager may need access to reports and configuration.
Make the handover process just as clear when someone joins or leaves. Remove access that is no longer needed, avoid shared administrator credentials and keep a named record of the accounts connected to the setup. The ICO?s organisational security guidance and GOV.UK data-protection information are useful references when your customer and staff processes involve personal information.
If the business uses automated follow-up for enquiries or appointment reminders, make sure staff understand the boundary between payment information, customer contact details and the AI Assistant services that may handle routine conversations. Keep payment data out of informal notes and unnecessary systems.
For a business owner, card machines Worthing decisions are strongest when the selection, staff training and end-of-day checks have all been tested together. If a provider makes a claim about authorisation or registration, use the Financial Services Register to check it through the appropriate official source.
Ask about support in operational terms
?Support available? is not enough detail. Ask who your staff contact, what information they should have ready, how a fault is diagnosed and what happens while the issue is being resolved. Also ask whether you will have a named record of your devices, administrator access and the actions already tried. Good support makes the next step obvious when a customer is standing at the counter.
Be specific about your own responsibilities too. A problem caused by a flat battery, changed Wi-Fi password or staff member using the wrong workflow may be resolved faster with a short opening checklist and basic training than with an urgent call. The goal is a calm, repeatable response?not a reliance on one person remembering everything.
Think ahead if you may add a second site
A single-location business does not need to buy a complicated multi-site process prematurely. But if you expect to add a second counter, pop-up, venue or location, ask whether your reports, products, permissions and customer rules can stay consistent. Planning this early avoids rebuilding the whole payment flow when the business grows.
Our guide to running multiple locations from one system explains the operational questions behind that step: which decisions stay local, which information is shared and how owners check performance without losing sight of individual sites. This is especially relevant if you are comparing card machines Worthing options for a business that trades in more than one setting.
Use a provider comparison sheet
Keep the comparison focused on the complete trading day. Record each provider?s answer to the same questions instead of relying on different sales language:
| Area to check | Question to ask | Why it matters |
|---|---|---|
| Trading location | Where and how will the terminal be used? | The equipment must fit the customer?s payment moment. |
| Workflow | How does a sale, receipt, refund or correction work? | Staff need a clear route when something changes. |
| Reporting | What does the owner review at the end of the day? | Payment activity needs context, not just totals. |
| Access | Who can do what, and how is access removed? | Controls should reflect real responsibility. |
| Support | What happens if the terminal or connection fails? | Busy-period issues need an agreed response. |
| Ownership | Which accounts, records and settings can the business access? | The setup should remain manageable after handover. |
Check that any marketing claim is clear and supportable before repeating it to customers. The ASA advertising codes and the FCA?s consumer information are high-trust starting points when you need to understand financial-services communications or verify a firm?s credentials through the appropriate official register.
Test the chosen setup before a major trading day
Once the equipment and workflow are agreed, test the realistic cases: a normal sale, a refund, a receipt request, a connection interruption, a staff changeover and the daily review. Do this before a launch, an event or a busy weekend?not when the queue is already forming. Give each test an owner and write down anything that needs changing.
Use feedback from the people who operate the process. A manager may see the reports, while a team member sees the customer?s confusion at the till. Both perspectives are needed. The best card machines Worthing setup is the one that makes payments simple for customers and accountable for the business.
For businesses that need payment activity to flow into a dependable customer follow-up process, the customer-management system we provide can be considered as part of the overall handover. The UK Finance information hub provides additional industry context. This helps keep card machines Worthing choices grounded in the complete trading process.
Key takeaways
Start with the way your customers pay, then build outward to connectivity, staff roles, refunds, reporting, support and future growth. A terminal should fit the trading day rather than forcing the business to work around it.
When comparing card machines Worthing options, insist on clear answers about workflow and ownership. Do not choose on a headline offer alone. The right solution is the one that gives the business a practical route for a normal sale, an exception and the end-of-day review.
Card machines Worthing businesses use every day should leave a clear transaction trail when a customer needs help.
Frequently asked questions
What should a Worthing business check before choosing a card machine?
Check where payments happen, whether staff need a fixed or portable setup, how connectivity works, what happens with refunds, who can access reports and how the device fits your existing sales process. Test the complete customer journey, not only a demonstration payment.
Can a card machine work alongside an EPOS system?
It can be part of a wider checkout setup, but the important point is how transaction data, orders, receipts, refunds and reports are handled. Ask what is connected, what remains separate and how staff will review exceptions.
How do I avoid a payment setup that creates extra work?
Map the day from opening check to closing review. Give every exception a clear owner, set proportionate staff permissions and make sure the business has access to the accounts and reports it will need after handover.
Want to review your card-payment setup?
If you want to compare your current process with the way you really trade, talk through your card-payment setup with our team. We will start with your customer journey and operational needs, then explain the options clearly.